By: Sobir Kurbanov and Eldaniz Gusseinov
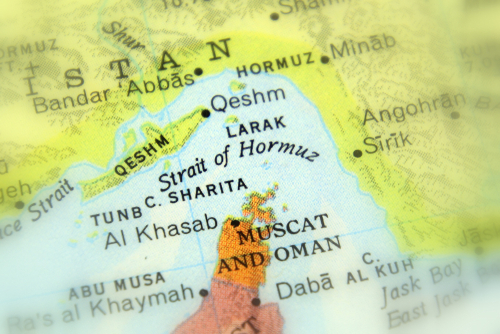
The renewed closure of the Strait of Hormuz, which followed the strikes on Iran of 28 February 2026, has tested world energy markets without producing the price spike that most forecasters expected, and the main reason lies in China. Chinese crude imports fell to 7.1 million barrels per day in June against a 2025 average of 11.6 million, while refinery utilisation dropped to 57.7 percent. For Central Asia the consequence arrives indirectly, because the same weak Chinese demand that has capped crude prices is also depressing the steel, iron ore and ferroalloy prices on which Kazakhstan’s metallurgical sector depends. The chokepoint that Beijing is building Central Asian corridors to bypass is now transmitting its own shock into the region through the very relationship those corridors are meant to deepen.
BACKGROUND:
The Strait of Hormuz carries roughly 20 percent of global oil consumption and a comparable share of liquefied natural gas, with no overland substitute at scale for most Gulf producers. The International Energy Agency warned on 12 August 2026 that Hormuz-related losses would cut global oil supply by 4.3 million barrels per day across the year, and that a projected demand increase of 850,000 barrels per day had reversed into a decline of 1.6 million. Prices rose sharply, yet the escalation that many analysts anticipated did not materialise, because the largest buyer withdrew from the market at the same moment.
On 5 March 2026 China ordered its largest refiners to suspend diesel and gasoline exports, and refiners began cutting throughput and bringing scheduled maintenance forward within days. A structural change compounded the cyclical one. GL Consulting estimates that Chinese gasoline consumption will fall 5.5 percent in 2026, the second steepest decline after the lockdown year of 2022, with retail prices up roughly 30 percent since late February and electric vehicles absorbing a growing share of the fleet. China entered the disruption holding approximately 300 million barrels of cheap crude accumulated over the 14 months before the war, a buffer that is substantial and finite.
Central Asia is too integrated into external markets to insulate itself from a shock of this size, and yet the shock does not arrive directly. Kazakhstan ships most of its crude westward through the Caspian Pipeline Consortium rather than through the Gulf, and the region’s hydrocarbon trade with China moves by pipeline, which protects volumes while leaving prices exposed. External disturbances therefore reach Central Asian economies through three intermediaries, Russia, China and the European Union. Residents of the region learned the shape of that transmission in 2022, when the war in Ukraine reached household budgets through remittances, Russian banking channels and rerouted transit rather than through any direct commercial link. The present episode follows a different path. In Temirtau and Aktobe, where employment is concentrated in steel and ferroalloy plants, and in Karaganda region, the connection between a maritime chokepoint 3,000 kilometres away and local order books is neither obvious nor remote.
IMPLICATIONS:
The transmission runs through Chinese construction. China accounts for roughly half of world steel output, and construction absorbs about 49 percent of that steel, down from 58 percent in 2020. The property downturn has deepened rather than stabilised. Between January and May 2026, housing sales declined 10.8 percent by floor area and 13.5 percent by value, new construction starts fell 22.6 percent and property investment fell 16.2 percent. Weak demand for steel pulls down the inputs that Kazakhstan sells into it.
According to analysis published by the Kazakh sector channel Metals and ESG Trends.KZ, falling steel demand has depressed prices for iron ore, ferrochrome, silicomanganese and ferrosilicon, with ferrosilicon down by approximately 30 to 35 percent and pressure building on Qarmet, ERG and the country’s independent ferroalloy producers. These figures come from a sector channel rather than from exchange data and should be treated as indicative, though they are consistent with the direction of Chinese construction indicators.
The oil shock is mainly a reversible supply-and-refinery disruption, although China’s underlying oil-demand trend is weakening. The ferrous challenge is more structural: China’s property sector is unlikely to restore the previous steel-demand regime, while Chinese overcapacity may intensify competition in Kazakhstan’s surrounding markets. Kazakhstan therefore needs not only short-term support, but a multi-year strategy of market diversification, productivity improvement and product upgrading.
The more consequential implication concerns the logic of integration itself. Chinese investment in processing industries across Central Asia has reached an estimated US$ 11.8 billion against US$ 4.1 billion in energy, reversing the historically extractive pattern, and the China-Kyrgyzstan-Uzbekistan railway began construction in 2025. Nightingale Int. argued in October 2024 that Beijing would move from buying commodities in the region to embedding it in Chinese industrial chains, a forecast that BYD’s full localisation of electric vehicle production in Uzbekistan has since borne out. That investment is driven substantially by the same chokepoint exposure now visible at Hormuz. Central Asia is therefore receiving Chinese capital because China needs a continental rear, and absorbing Chinese demand shocks because it is becoming one. Deeper integration raises both the opportunity and the correlation.
Transit revenue moves with the same cycle, since corridor volumes through Central Asia are weighted toward Chinese cargo, and traffic on the Trans-Caspian Transport Corridor reached 4.5 million tonnes in 2024 before easing in 2025. Kyrgyzstan and Tajikistan face a different version of the problem. Neither exports ferroalloys at scale, and both carry sovereign debt to China equivalent to roughly 9.5 percent and 6 percent of GDP respectively, servicing obligations denominated against a creditor whose own fiscal position is tightening. A prolonged Chinese slowdown compresses their repayment capacity and their construction pipelines at once.
Kazakhstan’s emerging answer is visible in Karaganda region, where new copper extraction and processing projects are advancing and diversification into non-ferrous metals has become a working scenario for the sector. The direction is sound, and the caveat is familiar. Announced projects are not deployed capacity, and copper demand is itself concentrated in Chinese buyers. Diversification that changes the commodity while leaving the customer unchanged reduces exposure to one construction cycle and not to one counterparty.
CONCLUSIONS:
The Hormuz disruption has demonstrated that Central Asia’s exposure to global shocks is now mediated primarily through China, and that this channel operates in both directions. Beijing’s search for continental redundancy is drawing capital, factories and corridors into the region, while the maritime vulnerability that motivates that search transmits demand shocks back along the same route. If flows through the strait normalise within 2026, the oil-linked component will unwind. The ferrous component will not, because it rests on a Chinese property contraction that predates the conflict and is expected to persist. For Central Asian governments the practical lesson concerns buyers rather than corridors. Multi-vector policy has been articulated mostly in terms of routes and creditors, and the present episode indicates that the diversification that matters most is the diversification of demand.
AUTHOR’S BIOS:
Sobir Kurbanov is an international development expert and fellow at Nightingale Int. with over 20 years of experience in partnership-building, complex market reforms, program management, and teaching policy reform, public sector economics, and industrial policy across Eurasia. His expertise spans macroeconomic management, public sector governance, private sector development, trade, investment climate, infrastructure, and IF4D portfolio management, with a strong track record of working with bilateral and multilateral donors (SECO, DFID, USAID, IMF, WB, EU, UN), governments, CSOs, and think tanks, and leading cross-functional teams to advance evidence-based policy solutions.
Eldaniz Gusseinov is co-founder and Head of Research at Nightingale Int. and a non-resident fellow at Ibn Haldun University’s Haydar Aliyev Center for Eurasian Studies.
By Suren Sargsyan
One year has passed since Armenia and Azerbaijan signed the Washington agreement under the direct mediation of President Trump. Nevertheless, the TRIPP project, an approximately 40-kilometer route that would constitute the shortest segment of the Middle Corridor, has yet to be implemented, leaving the broader project incomplete. Notably, the principal obstacles to its implementation originate neither in Armenia nor Azerbaijan but are predominantly external factors that continue to impede the project’s realization.

Image Source: Alam and Blancas (2026), Map O.1, "Main trade corridors connecting Asia and Europe." World Bank. CC BY 3.0 IGO.
BACKGROUND:
In August 2025, the Trump administration initiated a process aimed at normalizing relations between Armenia and Azerbaijan, in which an enhanced U.S. strategic presence in the South Caucasus, particularly in Armenia, was expected to play a significant role. A central element was the proposed Trump Route for International Peace and Prosperity (TRIPP) on Armenian territory, which would provide Azerbaijan with a direct connection to its Nakhchivan exclave without transiting Iran. The TRIPP would also offer Armenia and Azerbaijan an opportunity to strengthen their integration into the Middle Corridor, connecting Central Asia with Europe via the Caspian Sea, the South Caucasus, and Turkey.
In other words, the TRIPP would facilitate the development of the Middle Corridor through Armenia and Azerbaijan, which, according to the Trump administration, would contribute significantly to the normalization of Armenian-Azerbaijani relations. From a strategic perspective, the route also offers the prospect of transporting Central Asian energy resources to Europe while bypassing Russia and Iran. At the same time, it would provide Central Asian states with greater opportunities to diversify their export routes and reduce their dependence on China. Kazakhstan has shown particular interest in the project, as reflected in its deepening relations with Armenia, alongside its traditionally close ties with Azerbaijan.
Nevertheless, the project has experienced significant delays despite sustained efforts by Washington to advance its implementation. The U.S. has allocated financial resources for infrastructure development, established a dedicated fund to support the project, and appointed a manager with extensive knowledge of Armenia and its business environment, as well as direct ties to the Trump administration. Despite these measures, construction has yet to begin, and little information has been made available regarding the implementation process. The clearest indication of a potential timeline came from Azerbaijani President Ilham Aliyev, who recently stated that construction on Armenian territory may begin in early 2027.
IMPLICATIONS:
Developments over recent months provide a broader picture of the factors that have delayed the implementation of the TRIPP project on Armenian territory and, consequently, the project as a whole. The first concerns Iran. The U.S.-Israeli war with Iran has fundamentally altered the regional security environment, with Tehran targeting U.S. military bases and other facilities in neighboring states within range of its missile capabilities. Against this backdrop, TRIPP represents a U.S.-backed strategic transport route running directly along Iran’s northern border, in some places only a few hundred meters away. Its location and strategic significance have generated considerable concern in Tehran, which has publicly expressed its opposition to the project.
It therefore cannot be ruled out that the delays are partly linked to the negotiations between Iran and the U.S. and uncertainty over their outcome. In the event of renewed hostilities, the route could potentially become a target for Iran despite being located on the territory of a third country. Moreover, prior to the proposed implementation of TRIPP, Iran provided Azerbaijan with its shortest transit route to the Nakhchivan exclave, creating a degree of Azerbaijani dependence on Tehran that TRIPP would substantially reduce. Iran therefore also has an economic and geopolitical interest in the project’s development. Yet another significant obstacle concerns the railway component of TRIPP. A functioning rail connection is central to the project’s ambition to facilitate trade between Central Asia and Europe and is therefore of critical logistical importance to the viability of the corridor as a whole.
However, Armenia’s railway network remains under concession to the state-owned Russian Railways, with the agreement set to remain in force for a considerable period. Russia has shown little willingness to relinquish control, although recent developments suggest that the issue may be subject to negotiation. When the possibility of returning the railway network to Armenian control was raised, the head of Russian Railways emphasized that Russia had invested approximately US$ 400 million in Armenia’s railway infrastructure. This statement can be interpreted in two ways. Moscow may be signaling that it expects compensation for its investments as a condition for terminating the concession. Alternatively, it may indicate an interest in participating in the TRIPP project itself, with its existing investment potentially forming the basis for such involvement. In either case, control over Armenia’s railway infrastructure introduces a significant Russian dimension into the implementation of TRIPP.
This considerably complicates the situation, as both Moscow and Tehran are capable of exerting pressure on Armenia, albeit in different ways and in pursuit of their respective strategic interests. Any potential Russian participation in TRIPP would not, however, be a matter for Yerevan and Baku alone, as Washington and Moscow could potentially reach a separate agreement on Russia’s role in the project. At present, however, Iranian security concerns and Russia’s control over Armenia’s railway infrastructure remain among the principal external factors hindering the implementation of TRIPP.
CONCLUSIONS:
At present, Armenia and Azerbaijan have limited scope to advance the implementation of TRIPP independently. The outcome of potential negotiations between the U.S. and Iran, and ultimately the termination of hostilities, may prove critical to the project’s future. Should the parties pursue a diplomatic settlement, TRIPP may need to form part of a broader package of agreements between Washington and Tehran. The Russian dimension is equally complex. Moscow may seek compensation for its investments in Armenia’s railway infrastructure, a substantial burden for Armenia, or demand some form of participation in the project. The latter would present Washington with a strategic dilemma: whether to accommodate Russian involvement in a transport corridor whose broader geopolitical rationale includes reducing regional dependence on Russia.
In either case, the Trump administration would need to engage in substantive negotiations with Moscow, whether to agree on compensation or determine the terms of potential Russian participation in the project. The implementation of TRIPP therefore depends on a broader set of political and strategic agreements extending well beyond Armenia and Azerbaijan. Without such arrangements, the corridor will continue to entail significant geopolitical and security risks, potentially undermining its attractiveness to businesses seeking reliable routes for transporting goods between Central Asia and Europe.
AUTHOR’S BIO:
Suren Sargsyan is a PhD candidate Political Science. He holds LLM degrees from Yerevan State University, the American University of Armenia, and Tufts University Fletcher School of Law and Diplomacy. He is the director of the Armenian Center for American Studies.
By Erlan Benedis-Grab
On May 20, 2026 the UN General Assembly unanimously adopted a Turkmenistan-initiated resolution recasting neutrality as active stabilization rather than withdrawal from the global stage. Although it was ratified domestically in 2025, in July 2026 Turkmenistan became the last of the five Central Asian states to sign the Treaty on Friendship, Good-Neighborliness, and Cooperation for the Development of Central Asia in the 21st Century, nearly four years after it was opened for signature in 2022. On October 8, Ashgabat hosted the region’s newly consequential gathering, the Consultative Meeting of Central Asian and Azerbaijani heads of state (CMHS) in Avaza. Turkmenistan's recent actions suggest that a country once largely absent from multilateral institutions, is now an active participant in Greater Central Asian initiatives.
BACKGROUND:
Turkmenistan has, in the name of neutrality, pursued one of the most isolationist foreign policy orientations in Central Asia, if not the world. Unlike Kazakhstan and Kyrgyzstan, Turkmenistan is not a member of the Eurasian Economic Union; unlike Tajikistan, it is not a member of the Shanghai Cooperation Organization; and unlike Uzbekistan, it holds only associate status in the Commonwealth of Independent States. Saparmyrat Niyazov, or Turkmenbashi, intended to build neutrality into a sovereignty-as-state ideology, reinforcing his legitimacy, while also giving Turkmenistan a role as a neutral-venue country where opposing parties could meet.
With almost 35 years having passed since independence, though, neutrality in Turkmenistan has yielded mixed results. Its benefit stems mainly from its energy policy. Turkmenistan’s ability to reach various markets has depended mainly on relations with transit countries, where its neutral posture serves as a positive factor.
Yet, Turkmenistan’s economy remains in a precarious position, with persistent food, budget, and gas shortages. And, while it was able to serve as a host between warring parties during the Tajik and Afghan civil wars, it has not convened a major mediation since, while its neighbors have. Astana hosted the years-long talks on the Syrian conflict, one of the most violent in the contemporary period. Perhaps out of recognition of these shortcomings, Turkmenistan, while maintaining its policy of neutrality, is starting to emerge from its longstanding isolation.
Most notably, it has begun to participate more substantially in regional cooperation projects. The Consultative Meetings of the Heads of State of Central Asia (CMHS), the region’s standing summit format convening the five presidents, launched in 2018. It was at the CMHS's 2022 summit that Kazakhstan, Kyrgyzstan, and Uzbekistan signed the Treaty on Friendship, Good-Neighborliness, and Cooperation for the Development of Central Asia in the 21st Century. The treaty outlines cooperation agreements, including in critical areas like defense, law enforcement, water, energy, and a mutual-assistance clause. Tajikistan and Turkmenistan were both initially hesitant to sign on, citing the need to “complete all domestic procedures.” However, in August 2025 Tajikistan acceded, following a breakthrough in delimiting the borders of the Fergana Valley. Turkmenistan formally signed in July 2026.
Turkmenistan previously hosted the CMHS at Avaza in 2021, its only turn as host to date. Since then, the format has grown more consequential, admitting Azerbaijan as a full member in 2025. Turkmenistan’s return as host in 2026 therefore fits its broader pattern of renewed regional engagement.
Turkmenistan is also pursuing a renewed effort to participate more seriously in international intergovernmental organizations like the United Nations. In May 2026, Turkmenistan introduced the UN resolution “The Role and Importance of a Policy of Neutrality in Maintaining and Strengthening International Peace, Security and Sustainable Development” which the General Assembly adopted. The same language Turkmenistan once used to keep the world at a distance now draws it closer.
IMPLICATIONS:
Signing onto a regional cooperation treaty, hosting the CMHS, and making diplomatic pushes at the UN mark a Turkmen shift from isolation. Turkmenistan’s recent actions suggest a country poised to try to take on a bigger role in world affairs, motivated by a fear of being left behind, the changing external environment, the need for economic diversification, and regime legitimacy.
Serdar Berdimuhamedov, who became president in 2022, has continued a doctrinal shift, begun under his father, away from Turkmenbashi’s “permanent neutrality” towards what might be called “active neutrality.” This policy seeks to utilize Turkmenistan’s non-aligned status as a platform for diplomacy.
aPreviously, Turkmenbashi’s “permanent neutrality” was essentially a shield for disengagement, codified within the constitution. The changing nature of Russia's role in Central Asia partly explains this shift as well. That shield was primarily aimed at one country: Russia. Non-alignment justified staying out of Russian-led integration projects; however, Moscow's leverage has since thinned. China is moving in, and Russia's attention is fixed west, on Ukraine, so Turkmenistan has had to update its strategy to this new environment.
Turkmenistan is pursuing renewed engagement with its neighbors. Turkmenistan’s signing of the Treaty on Friendship, Good-Neighborliness, and Cooperation for the Development of Central Asia in the 21st Century is the clearest marker of this. Although formally binding, the treaty is noncommittal, with no automatic trigger or enforcement mechanism. This is a significant factor in Turkmenistan’s accession, even though it was delayed. If a security threat arises, the response is “determined through bilateral consultations and within the framework of Consultative Meetings.” That falls well short of the CSTO treaty, which requires members to “immediately provide … the necessary help, including military one,” or the CIS treaty, which permits “the use of the Armed Forces” in individual or collective self-defense.
Regionalism is advancing regardless of Turkmenistan, and Ashgabat appears unwilling to be the one state left out of it. Kazakhstan and Uzbekistan have driven the push for deeper integration—and they have been largely successful in this. Intra-regional trade nearly doubled from 2020 to 2025, while the Fergana Valley states settled their long-running border dispute. Staying outside would have left Turkmenistan negotiating from outside a structure its neighbors had already built without it.
Thus, by hosting the Avaza summit on October 8, Turkmenistan has a chance to set an important agenda. Ahead of the summit, Ashgabat circulated a draft agenda to its partners spanning security, diplomacy, trade and logistics, climate and water, and humanitarian cooperation. As Kazakhstan pointed out in July, the next steps should be to develop a concrete action plan as the CMHS format moves along.
Economic diversification is an important focus for Turkmenistan. It remains constrained by near-total reliance on natural gas exports, the overwhelming majority bound for China. While mutual-assistance commitments are a tougher sell, proposals like Tajikistan’s prospective joint oil refinery are the kinds of economic initiatives that appeal to Ashgabat.
International validation of Turkmenistan’s neutrality reinforces the legitimacy of the ruling family, making prestige a significant motivator for Ashgabat. The May 2026 UN resolution gave neutrality a standalone General Assembly agenda item, strengthening Turkmenistan’s diplomatic profile. This momentum also supports its bid for a 2031–2032 UN Security Council seat, which would provide another significant source of international prestige.
CONCLUSIONS:
This is Turkmenistan’s most substantive year of regional engagement since 1995. Ashgabat chose its engagement moves for their low cost. The CMHS treaty is noncommittal, the UN resolution is declaratory, and hosting is a rotational duty. Turkmenistan maintains its neutral doctrine, but through active diplomacy rather than diplomatic isolation. This posture will likely hold in the long term because its drivers reinforce the need for engagement. Turkmenistan still leans almost entirely on gas sales to China, whereas Central Asia continues to build structures regardless of Turkmen involvement. And the international promotion of neutrality plays well at home. The limits to Turkmenistan’s shift are also clear and it can be expected to continually abstain from the usual multilateral institutions. If regional cooperation deepens toward binding obligations at Avaza or beyond, Ashgabat’s commitment will be tested.
AUTHORS BIO:
Erlan Benedis-Grab is a Junior Fellow at the Central Asia-Caucasus Institute. He holds a dual B.A. in Economics and Central Eurasian Studies at Indiana University Bloomington, and his research focuses on Central Asia, International Trade, and Energy Politics. He can be reached at This email address is being protected from spambots. You need JavaScript enabled to view it. .
By Nargiza Umarova
The Islamic Republic of Iran is strengthening the Afghan dimension of its transport diplomacy, while also developing partnerships with Central Asian states. Several notable events have recently occurred in this area, and a collective analysis of these developments demonstrates Afghanistan’s active involvement in the expanding network of Eurasian overland routes. China is providing practical support for this within the framework of its Belt and Road Initiative. Beijing’s strategy involves diversifying east-west logistics routes via Central Asia to minimize the growing risks of uncertainty in maritime shipping. Uzbekistan is expected to benefit particularly from this progress, as it prioritizes southern transit corridors and maintains pragmatic policies towards both Afghanistan and Iran.
BACKGROUND:
In June 2026, an Afghan delegation led by Deputy Minister for Railways, Mawlavi Mohammad Ishaq Sahibzada, visited Iran to discuss transport logistics infrastructure projects, including the construction of the Herat–Mazar-i-Sharif railway. The parties discussed technical specifications, standards, financing mechanisms and the stages of project implementation. Prior to the meeting in Tehran, media reports had indicated that Afghan commercial banks were willing to invest in the new railway line connecting the provinces of Balkh and Herat, estimated to cost US$ 780 million. It was later revealed that Iranian companies would undertake the construction of the infrastructure facility in exchange for participating in the development of Afghanistan’s mineral resources.
The Herat–Mazar-i-Sharif transport line will serve as an extension of the cross-border trade route that originates in the Iranian city of Khaf, and will be a key component of the Afghan section of the Five Nations Railway Corridor (FNRC), which is approximately 2,100 km long. The FNRC extends to Kashgar in China and utilizes a uniform 1,435 mm standard gauge, crossing the borders of two Central Asian states: Tajikistan and Kyrgyzstan. In a global context, this will create a more competitive continental East-West Corridor, in which Afghanistan and its northern neighbors will play a pivotal connecting role.
The strategic importance of the Herat-Mazar-i-Sharif railway project is determined by its potential to connect Iran and Türkiye with the Central Asian republics and China via Afghanistan. It is worth noting that Ankara is a third party to the agreement on the joint construction of a railway to Mazar-i-Sharif, which was signed in Istanbul during the 36th regional meeting of the International Union of Railways in October 2025.
In light of the Strait of Hormuz crisis triggered by the military standoff with the U.S., it has become critical necessity for Tehran to establish additional transport routes to China, one of its largest trading partners. Beijing is interested in both the Iranian market and the Islamic Republic’s extensive transit capabilities. On May 25, 2025, the first freight train departed from Xi’an, China, bound for the Iranian dry port of Aprin, marking the official launch of direct land transport between the two countries. The Xi’an-Aprin railway route passes through Kazakhstan and Turkmenistan, making use of the Uzen (Kazakhstan)-Bereket (Turkmenistan)-Gorgan (Iran) railway line. This line was opened in 2014 and forms part of the eastern route of the International North-South Transport Corridor.
Within the framework of the six-party meeting mechanism for heads of railway administrations, a China-Kazakhstan-Uzbekistan-Turkmenistan-Iran-Türkiye/EU railway corridor is being developed. This involves Uzbekistan in container transport along the southern branch of the East-West Corridor. This development forms part of the wider initiative to establish the China-Europe Railway Express Economic Corridor under the Belt and Road Initiative. The expansion of the network of freight routes connecting Chinese and Central Asian cities should also be viewed in this context. Since early 2026, several regular and test block trains have been launched from industrial and economic centers in China, such as Chongqing, Sichuan, Jiangsu, Hubei and Xining, bound for Central Asian countries, with the potential to extend into Iran and beyond.
IMPLICATIONS:
The practical progress being made on constructing the Herat-Mazar-i-Sharif railway line, alongside the already operational Khaf-Herat railway, reflects Iran’s desire to diversify its freight transport corridors, particularly in view of the ongoing risks of disruption to maritime shipping in the Strait of Hormuz. Tehran is therefore prioritizing the expansion of rail connections with Afghanistan and its Central Asian partners. Implementing the Herat-Mazar-i-Sharif infrastructure project is central to achieving this objective, as announced by the Iranian government in August 2026.
In light of the escalation of the Afghan-Pakistani conflict, the rail link between Iran and Afghanistan has given Kabul a significant opportunity to access the markets of the Persian Gulf states, Türkiye and the EU, offsetting the costs resulting from the temporary lack of access to the seaports of neighboring Pakistan. This has also boosted Iranian-Afghan trade, with an annual volume reaching US$ 3.6 billion. Similarly, bilateral freight traffic has sharply increased. From March 2025 to March 2026, over 640,000 tons of cargo were transported via the Khaf-Herat railway, compared to fewer than 15,000 tons during the previous period. Monthly volumes have already approached 130,000 tons, and projections indicate growth to 160,000 tons per month, or 1.5 million tons per year.
It is estimated that, once the Khaf-Herat railway line is fully operational, the annual volume of interstate freight traffic could increase to 3 million tons, and transit freight to 1.7 million tons. These figures are in line with Tehran’s ambitious plan to increase the volume of cargo transported by rail to 60 million tons per year. This goal will be achieved by developing North-South and East-West international transport corridors, which will require close cooperation with neighboring countries, including those in Central Asia. Tehran has already announced plans to increase rail freight traffic with Kazakhstan to 5 million tons per year, with Turkmenistan to 4 million tons, and with Uzbekistan to 2 million tons.
In order to speed up the transportation process and remove the physical barriers hindering the movement of cargo, Iran has reached agreements with Uzbekistan and Turkmenistan regarding the passage of its wagons, which should ensure their free movement throughout the CIS. However, these agreements have not yet been implemented.
CONCLUSIONS:
A review of Afghanistan’s foreign policy activities over the past few months reveals a noticeable synchronization of efforts between Kabul and Tehran in promoting the construction of a railway line to Mazar-i-Sharif. This project would establish an additional transport link to Central Asia via the Uzbek border. In this context, the visit of an Afghan technical delegation to Tashkent on July 22, 2026, is noteworthy. During negotiations with the Chairman of the Board of Uzbekistan Temir Yullari, a joint-stock company, the parties held detailed discussions on commencing engineering surveys to prepare a feasibility study for the Trans-Afghan (Kabul) Railway Corridor, as well as the possible transfer of project documentation and a preliminary feasibility study for the construction of the Herat-Mazar-i-Sharif railway to the Afghan side. The parties also addressed the modernization of infrastructure at Hairatan station, the construction of new warehouse complexes and an additional 1,650-meter access track at Naibabad station, which is located along the Hairatan-Mazar-i-Sharif route. In April 2026, Uzbek specialists had already laid 1,000 meters of access tracks on this section to simplify and accelerate cargo handling.
On July 27, an official meeting took place between Afghanistan’s Minister of Public Works, Mullah Mohammad Issa Sani, and Uzbekistan’s Deputy Prime Minister, Jamshid Khodjayev. According to Afghan sources, the Uzbek authorities expressed an interest in investing in the railway network between Herat and Mazar-i-Sharif. However, this information has not been officially confirmed by Tashkent.
If Uzbekistan is intent on contributing to the implementation of the new project, it could encourage the country to participate in developing the Five Nations Road. Although the original route was designed to bypass Uzbekistan, the construction of the China-Kyrgyzstan-Uzbekistan railway offers the potential to connect with the FNRC via a spur extending into Tajikistan through the Sughd section. This would enable the route to bypass the congested transport hub in Tashkent, shortening the journey to Afghanistan by several hundred kilometers.
AUTHOR’S BIO:
Nargiza Umarova is a Head of the Center for Strategic Connectivity at the Institute for Advanced International Studies (IAIS), University of World Economy and Diplomacy (UWED), and an analyst at the Non-governmental Research Institution ‘Knowledge Caravan’, Tashkent, Uzbekistan. Her research activities focus on developments in Central Asia, trends in regional integration, and the influence of great powers on this process. She also explores Uzbekistan’s current policy on the creation and development of international transport corridors. She can be contacted at This email address is being protected from spambots. You need JavaScript enabled to view it. .
Feature Articles
|
Earlier Articles
|
The Central Asia-Caucasus Analyst is a biweekly publication of the Central Asia-Caucasus Institute & Silk Road Studies Program, a Joint Transatlantic Research and Policy Center affiliated with the American Foreign Policy Council, Washington DC., and the Institute for Security and Development Policy, Stockholm. For 15 years, the Analyst has brought cutting edge analysis of the region geared toward a practitioner audience.
Sign up for upcoming events, latest news, and articles from the CACI Analyst.