By: Stephen Blank
Much has been written about the decline of Russian influence in Central Asia and the rising self-assertion of local governments. Most of this commentary focuses on Kazakhstan and Uzbekistan, the two richest and strongest states in Central Asia. However, the decline of Russia’s capacity for dominating Central Asia and local governments’ greater freedom of action has become equally visible to states like Tajikistan that are often overlooked. Dushanbe cannot and has not gone as far as Astana and Tashkent and frequently acts out of necessity as much as choice. Nevertheless, the signs of its growing capacity and of Russia’s parallel decline are mounting.
BACKGROUND:
Even though Tajikistan imported 91 percent of its petroleum products from Russia in the first half of 2026, it began importing Iranian oil in August because it cannot rely exclusively on continuing Russian supplies. Ukraine’s attacks on Russian refineries have forced Moscow to impose export restrictions that have rebounded on Central Asian countries like Tajikistan. Thus, while most of its energy imports originate in Russia, Tajikistan has had to risk falling afoul of U.S. sanctions on Iran to sustain its economy and other Central Asian states have also had to follow suit for the same reason.
This is far from the only example of Russia’s decline. Hitherto, Russia has been virtually the sole source of Central Asian militaries’ armaments. Now, due to the pressures imposed by the demands emanating from the war in Ukraine, foreign sanctions on components, and the lackluster performance of Russian weapons, that is no longer the case for all the Central Asian states. Tajikistan and Turkmenistan have acquired India’s Akash air-defense system. Tajikistan has also purchased China’s HQ-17AE air defense systems, whereas Uzbekistan and Turkmenistan also operate Chinese systems.
These purchases of diverse and heterogeneous systems from multiple suppliers generate challenges of management and integration into a functioning whole. Nonetheless, they send an unmistakable message that Russia can no longer play an exclusive role as the sole regional security manager. In many cases, Russia will not be able to maintain supply chains or provide repairs to aging equipment, thus its ability to provide for Tajikistan’s security is obviously declining.
This does not imply that Tajikistan can or will go as far as Kazakhstan and Uzbekistan have gone in diversifying their foreign policy options to enhance their actual sovereignty and independence. For example, Tajikistan, in an apparent effort to placate Russia, has begun the procedure for withdrawing from the International Criminal Court (ICC), which has indicted President Vladimir Putin for war crimes in the war against Ukraine. Indeed, when Putin visited Dushanbe in 2025, Tajikistan refused to arrest him. This led the ICC to find Tajikistan in breach of its obligations, leaving it no choice but to initiate the withdrawal. In a contest between the ICC and Russia, Tajikistan obviously chose Russia.
IMPLICATIONS:
Nevertheless, Tajikistan has shown and will continue to show that it is responsive to international developments beyond Russia. Tajikistan’s Humo Bank warned its Russian clients that unless they visited one of its offices in Tajikistan and submitted to a biometric identification by September 30, their cards would be blocked starting on October 1. Although Humo Bank cited the need to protect its clients from fraud; apparently the real reason was Western pressure operating through Visa Direct to threaten sanctions unless Humo Bank stopped allowing certain clients to use it to circumvent sanctions.
Although Humo Bank operates in Tajikistan under license from the government; it is owned by the Japanese Investment holding firm, Gojo & Co, and is therefore vulnerable to Western pressure. However, what is interesting in this case is that Tajikistan acceded to that pressure targeting its Russian customers.
Moreover, in this context Humo Bank was not the only bank that yielded to Western pressure. For example, Revolut Bank stopped accepting top-ups from credit cards issued in Tajikistan, Kyrgyzstan, and Uzbekistan for EU residents, claiming that payment systems had classified those countries as high-risk. Tajikistan took advantage of foreign pressure to limit Russian influence in its banking system. And it did so despite the fact that its economy depends to a great degree on remittances from Tajik migrant workers in Russia and the ensuing unimpeded flow of capital through Russian banks.
None of this suggests that Tajikistan can or will emulate the actions of Kazakhstan and Uzbekistan in making extensive deals with Washington, Brussels, the Gulf states, and others. Tajikistan does not have these capabilities, nor will it attain them anytime soon. Its ability to play China off against Russia, and to balance other external actors against Moscow and Beijing, is much lower than that of Astana and Tashkent.
Yet the decline of Russia’s capability in the economic as well as the military sector is both creating more space for independent action on Tajikistan’s part and the necessity for it to defend its own interests. Moreover, Russia’s decline has led other foreign actors, including Western banking and financial interests as well as Chinese and Indian defense exporters, to fill the ensuing vacuum created by Russia’s increasing incapacity.
In cases where the costs to Tajikistan from striking at Russian interests outweigh the benefits it might gain, as in the example of the ICC, Dushanbe has refused to antagonize Moscow. This pattern is likely to continue for some time to come, especially since the situation in and around Afghanistan, which is a vital security interest of Tajikistan that it cannot manage by itself, becomes more precarious. However, as Tajikistan continues to work more cooperatively with other Central Asian and foreign governments, its ability to stand up for itself will grow.
CONCLUSIONS:
Increasingly the trends towards regional self-assertion and involvement with partners beyond Russia and China are becoming more prominent in Central Asia’s politics. The fact that this is occurring not only with regard to Uzbekistan and Kazakhstan, but also in Tajikistan’s case suggests that these trends are putting down lasting roots. Therefore, despite the imbalance of capabilities between Moscow and Dushanbe, we should expect to see more examples Central Asian including Tajik self-assertion. Yet we should also, based on the mounting constraints upon Russia, see more examples of its growing incapacity to enforce unilateral dominance over local governments.
AUTHOR’S BIO:
Stephen Blank is a Senior Fellow with the Foreign Policy Research Institute, www.fpri.org.
By: Vusal Guliyev
Azerbaijan, Kazakhstan, and China increasingly seek to strengthen the Middle Corridor as a trans-Eurasian trade and logistics route. China’s proposal to extend Lianyungang Port’s existing logistics chain to Baku, alongside expanding container capacity at Aktau and new multimodal transport agreements, reflects a shift toward integrating previously separate infrastructure projects. Building on the existing Lianyungang–Khorgos–Aktau “Three Nodes” logistics chain, the proposed extension to Baku could further integrate transport networks across China, Central Asia, and the South Caucasus, strengthening freight connectivity with European markets. It could also create opportunities for Japan and South Korea to diversify their trade and energy routes amid disruptions to traditional supply chains. However, its long-term viability will depend on whether the participating countries can coordinate railway services, port operations, customs procedures, and digital systems to deliver reliable, cost-effective, and commercially competitive freight services.
BACKGROUND:
On September 9, 2026, Kazakh President Kassym-Jomart Tokayev’s interview with Xinhua highlighted the growing importance of the Azerbaijan–Kazakhstan-China logistics connection. The same day in Baku, at the CICA Conference of Port Authorities, Jiang Wei, Vice President for External Relations of Lianyungang Port, proposed incorporating Baku into the existing Lianyungang–Khorgos–Aktau “Three Nodes” logistics chain.
At the sidelines of the conference, Rovshan Rustamov, Chairman of Azerbaijan Railways (ADY), met with representatives of China’s Shanghai International Port Group (SIPG), NIZE Tech, and Lianyungang Port. Discussions focused on developing the Lianyungang–Baku route, expanding regular container and block-train services, attracting additional Chinese cargo bound for Europe, and introducing smart-port technologies and digital solutions. The participants also highlighted the importance of exchanging information on cargo forecasts, train schedules, and logistical requirements to improve coordination between railway and port operations and strengthen the Middle Corridor’s competitiveness.
On September 8, Tahir Budagov, Deputy Chairman of Azerbaijan’s ruling New Azerbaijan Party (YAP), met with a Chinese delegation led by Liu Haixing, Minister of the International Department of the Communist Party of China (CPC) Central Committee. Their discussions focused on trade, transportation, the Belt and Road Initiative (BRI), the Zangezur Corridor, and Beijing’s support for Azerbaijan’s deeper engagement with the Shanghai Cooperation Organization (SCO).
These developments build on a growing network of infrastructure investments and bilateral agreements established in previous years, supported by sustained high-level engagement among the participating governments. On July 3, 2024, Azerbaijan and China adopted a Joint Declaration on the Establishment of a Strategic Partnership in Astana. The declaration committed both countries to strengthening cooperation on the Middle Corridor and accelerating the development of China–Europe freight-train services. That same day, KTZ Express, Aktau International Commercial Sea Port, and Lianyungang Port Group reached an agreement on the key terms for establishing a joint venture to develop a container hub at Aktau Port. The US$ 96 million project envisaged the construction, management, and operation of a new container terminal with a planned annual capacity of 500,000 TEUs (twenty-foot equivalent unit).
In September 2024, Lianyungang Port Group Co., Ltd., Kazakhstan Express Rail Company, and Aktau International Commercial Sea Port signed agreements to implement the Aktau Port Container Hub project. The facility officially began operations on June 9, 2025, strengthening Kazakhstan’s transit capacity along the Trans-Caspian International Transport Route. Meanwhile, in November 2024, during COP29 in Baku, Azerbaijan, Kazakhstan, and China’s Xi’an Free Trade Port Construction and Operation Co., Ltd. agreed to establish a joint venture to develop an intermodal cargo terminal on an initial 40-hectare site at the Port of Baku in Alat. In April 2025, the transport ministers of Azerbaijan and China inked the Agreement on International Multimodal Transportation in Beijing. In July 2025, Azerbaijan Railways (ADY) concluded separate agreements with China State Railway Group and Xi’an Free Trade Port to strengthen the Baku–Tbilisi–Kars railway, expand rail transit, and establish a container yard at Xi’an with an annual handling capacity of 20,000 TEUs.
These joint initiatives establish the foundations for a logistics network connecting Chinese inland and coastal transport hubs with Kazakhstan’s railways and Caspian ports, Azerbaijan’s transport infrastructure, and onward routes to Europe.
IMPLICATIONS:
The proposed extension of the Lianyungang–Khorgos–Aktau chain to Baku represents a shift from developing individual transport projects toward coordinating a broader logistics network. The initiative seeks to connect existing facilities through more integrated freight services and information systems.
Azerbaijan’s greater integration into the trans-Eurasian maritime network could strengthen China’s connectivity with markets west of the Caspian Sea and improve links between its inland logistics centers and European destinations. With an annual cargo throughput of 367 million tons and 7.1598 million TEUs, Lianyungang Port serves as a key transit gateway connecting China’s maritime trade routes with its inland transport networks, while Khorgos facilitates cross-border rail connectivity between China and the wider Caspian–Central Asia region. Aktau provides access to the Caspian Sea, while Baku serves as a gateway to the South Caucasus and onward transport routes through Georgia and Türkiye. With a planned annual cargo-handling capacity of 25 million tons, the Port of Baku is positioned to play a vital role in strengthening Eurasian connectivity. Closer integration with the Lianyungang–Khorgos–Aktau network could reinforce Azerbaijan’s strategic importance in the trans-Caspian trade and logistics ecosystem.
Closer coordination with Baku is also enabling Astana to better leverage its Caspian logistics infrastructure and reinforce its position along westbound trade routes. To expand the Middle Corridor’s capacity, Kazakhstan plans to increase the combined cargo-handling capacity of the Aktau and Kuryk ports from 21 million to 30 million tons through modernization efforts. Authorities in Azerbaijan and Kazakhstan have been working to improve trans-Caspian freight transport along the Baku–Aktau route. As part of these efforts, an electronic data exchange system was introduced between the two ports in April 2025 to enhance inter-port coordination, streamline cargo operations, and improve freight efficiency across the Caspian basin.
Moreover, given the proximity of Lianyungang Port to major maritime hubs in Japan and South Korea, the Lianyungang–Khorgos–Aktau–Baku logistics chain could provide both countries with an additional trade route into the wider Caspian-Central Asian region. Amid escalating geopolitical tensions, sanctions-related constraints, and disruptions linked to the war in Ukraine and the ongoing conflict in the Persian Gulf, the Middle Corridor is gaining prominence as a potentially more resilient supply channel for both countries. Tokyo and Seoul have already expanded their engagement with Central Asia through multilateral cooperation frameworks that strongly support their involvement in the Middle Corridor’s development.
Despite the expansion of transport infrastructure, integrating the Lianyungang–Khorgos–Aktau–Baku route into a commercially competitive logistics network will require overcoming several operational challenges. Differences in railway timetables, port-handling procedures, customs documentation, and cargo-tracking systems can cause delays at transfer points, particularly where shipments move between rail and maritime transport. Limited digitalization of transport and customs procedures, together with the lack of interoperable information systems and real-time data sharing among participating countries, could further hinder cargo tracking, information exchange, and coordination among logistics operators.
Caspian crossings add another layer of complexity, as vessel availability, weather conditions, and the coordination of loading and unloading operations can affect transit schedules. The Caspian Sea’s declining water levels pose an additional long-term challenge by potentially reducing navigable depths, restricting vessel access to ports, and increasing dredging requirements and transportation costs. These conditions could further disrupt maritime operations and undermine the reliability of transit schedules along the Middle Corridor. Ostensibly, infrastructure expansion alone will not guarantee higher freight volumes if tariffs remain uncompetitive or cargo owners cannot rely on predictable delivery times.
Addressing these constraints will require closer coordination among railway operators, port authorities, customs administrations, and logistics companies, supported by interoperable digital systems and reliable information-sharing mechanisms. Efficient transshipment operations, adequate vessel capacity, streamlined customs procedures, and dependable rail connections will be essential to reducing logistical uncertainty and facilitating the movement of intercontinental cargo across the Caspian Sea.
CONCLUSIONS:
The developments outlined above indicate that Azerbaijan, Kazakhstan, and China are moving toward closer coordination in developing the Middle Corridor’s logistics network. The proposed integration of Baku into Lianyungang’s “Three Nodes” logistics chain builds on container-handling infrastructure at Aktau, plans for an intermodal terminal at the Port of Baku, and agreements connecting Chinese logistics hubs with Azerbaijan’s railway network. The key challenge lies in transforming these individual projects into reliable, integrated freight services. Progress in these areas could further consolidate Azerbaijan’s role as a regional transit hub, strengthen Kazakhstan’s position in Caspian connectivity, and expand China’s access to markets across the wider Caspian–Central Asian region and beyond.
AUTHOR’S BIO:
Vusal Guliyev is an Indo-Pacific and Eurasian Affairs Analyst with professional and academic experience spanning leading research institutions, think tanks, and fellowship programs across Azerbaijan, Türkiye, China, Japan, South Korea, and the United States. He currently works as a Leading Advisor at the Baku-based Center for Analysis of International Relations and Multiculturalism (AIR Center).
By: Mathieu Lemoine
South Korea’s first summit with all five Central Asian presidents, held in Seoul on September 16, gave new institutional weight to a relationship more than three decades old. Critical minerals and supply-chain security featured prominently, but the significance of the new framework will depend less on how many resources South Korea secures than on what its engagement leaves behind in Central Asia. Seoul wants more resilient and diversified supply chains. Central Asian governments increasingly want foreign interest in their resources to generate processing, technology, skills and industrial development. Seoul is seeking diversification; Central Asia is seeking transformation.
BACKGROUND:
The summit did not mark South Korea’s arrival in Central Asia. The Korea-Central Asia Cooperation Forum has existed since 2007, while successive governments in Seoul have incorporated the region into broader Eurasian strategies. Moon Jae-in’s New Northern Policy and Yoon Suk-yeol’s K-Silk Road initiative both preceded the current framework, and the summit itself had originally been envisaged under Yoon.
What changed in September was the level of institutionalization. For the first time, South Korea and all five Central Asian states met in a common presidential format, upgrading cooperation that had previously been conducted mainly through bilateral relations and ministerial-level mechanisms. An inaugural C5+1 Industry Ministers’ Meeting also created a multilateral channel focused on industry, supply chains and critical minerals.
The new framework nevertheless reflects a changing international economic environment. Russia’s full-scale invasion of Ukraine, disruptions to global trade and growing competition over strategic inputs have increased South Korea’s incentive to diversify sources of key materials. Matteo Fumagalli, Professor of International Relations at the University of St Andrews, sees this emphasis on resilience as an addition to longstanding Korean priorities rather than a fundamental change of direction.
Central Asia is attractive in this context because of its reserves of uranium, tungsten and other strategic resources. South Korea, meanwhile, depends heavily on imported minerals for industries including semiconductors, batteries and steel.
But the priorities announced around the summit went beyond extraction. The first C5+1 Industry Ministers’ Meeting identified industrial infrastructure, critical-mineral supply chains, technology cooperation and talent development among its main areas of work. Importantly for Central Asian governments, the stated ambition also included refining, smelting, higher-value processing and manufacturing.
The question is whether this political and institutional momentum can now be converted into commercially viable projects.
IMPLICATIONS:
The first test of the new framework is not how many agreements are signed, but what kind of economic relationship develops around Central Asia’s resources.
For the region, increasing mineral exports would represent only a limited form of success. The more consequential question is whether Korean investment creates capabilities that remain locally: processing facilities, engineering expertise, laboratories, trained workers and suppliers able to meet demanding industrial standards.
This distinction is particularly important when governments speak of technology transfer. Purchasing Korean machinery does not in itself create technological capacity. Aidar Kurmashev of the Kazakhstan Institute for Strategic Studies argues that meaningful transfer requires local engineers able to control production processes, laboratories capable of testing quality, maintenance capacity and suppliers able to meet industrial specifications.
Kazakhstan’s automotive sector provides an indication of what a deeper model of cooperation could look like. Korean-backed vehicle production has increasingly been accompanied by efforts to localize components and connect industrial investment with technical education. Its longer-term significance will depend on whether domestic suppliers eventually acquire capabilities that allow them to serve several customers rather than remain dependent on a single assembly operation.
This is where South Korea could offer something distinctive. Korean companies can combine technology and production management with knowledge of the standards required by advanced industrial customers. If those capabilities are embedded locally, they could help Central Asian firms enter production networks that would otherwise be difficult to access.
Yet the constraints are considerable. Central Asia is landlocked, divided into several relatively small markets and geographically distant from Korean production centers. Transport therefore remains expensive and complex. The Middle Corridor has attracted growing attention as Central Asian governments seek additional routes across the Caspian and South Caucasus, but from South Korea even an overland Eurasian connection requires goods first to reach the continent by sea because transit through North Korea is unavailable.
A second challenge concerns the regional character of the new framework. A C5+1 mechanism does not automatically create a regional economic relationship.
Kazakhstan and Uzbekistan have traditionally dominated South Korea’s engagement with Central Asia because of their larger markets, industrial bases, resource endowments and extensive human ties. Kyrgyzstan, Tajikistan and Turkmenistan have different economic structures and offer different forms of cooperation. Replicating the Kazakh or Uzbek relationship across all five countries is therefore neither realistic nor necessary.
A more viable model would combine bilateral investment with regional economic effects. Large industrial projects will continue to be negotiated primarily between individual governments and companies, but they can acquire a regional dimension if they generate supply chains, services and commercial links across borders.
Smaller Central Asian economies do not each need a Korean assembly plant to benefit from deeper cooperation. They could participate through specialized suppliers, logistics, technical services, training or other activities connected to regional production networks. Jieon Lee, Professor in the Department of Central Asian Studies at Hankuk University of Foreign Studies, also points to areas such as water management, human-resource development, environmental policy and digital governance, where cooperation could create regional benefits even if not every country participates in the same way.
This differentiated model also changes how South Korea’s growing role should be understood geopolitically. Central Asian governments are not looking for Seoul to replace China, Russia, the European Union, Japan, Türkiye or the Gulf states. They are seeking additional options.
The value of diversification lies not in accumulating foreign partners for its own sake, but in reducing structural dependence. A producer with several potential customers, access to alternative technologies, multiple financing sources and more than one workable transport route has greater room for maneuver. Adding another external actor without changing those underlying dependencies achieves much less.
South Korea enters this environment with important advantages. It retains a comparatively non-threatening profile in Central Asia and does not carry the same geopolitical baggage as some larger powers. Korean culture, education and business also enjoy considerable visibility, particularly in Kazakhstan and Uzbekistan.
But this goodwill should not be taken for granted. If Korean engagement becomes associated primarily with securing access to raw materials, it risks reproducing the same frustrations Central Asian governments increasingly express toward extractive forms of external partnership. The credibility of the new framework will therefore depend on whether industrial cooperation produces visible local value.
That makes implementation more important than diplomatic architecture. The summit and the new C5+1 mechanisms can create political direction and regular channels for cooperation, but they cannot by themselves make projects commercially viable. Financing, transport costs, regulatory conditions, reliable customers and private-sector incentives will ultimately determine which initiatives move forward.
CONCLUSIONS:
The September summit has institutionalized South Korea’s relationship with Central Asia. It has not yet transformed it.
The decisive phase will take place below the level of presidential diplomacy. Memoranda must become feasibility studies, financing agreements, actual investment and operating facilities. Progress should therefore be measured not only by the volume of minerals exported or the number of agreements announced, but by whether cooperation produces processing capacity, competitive suppliers, skilled engineers and commercially viable production networks.
The C5+1 format should likewise not be judged by whether it creates identical Korean relationships with all five Central Asian states. Kazakhstan and Uzbekistan will remain the principal economic anchors, while smaller economies can participate through supply chains, services and regional initiatives.
South Korea does not need to become Central Asia’s dominant external actor for the new framework to matter. Its opportunity lies in the overlap between Seoul’s search for resilient supply chains and the region’s search for investment, technology and greater productive capacity. If that overlap creates durable local capabilities, the summit may mark a substantive change. If it produces mainly new memoranda and meetings, the institutional architecture will have advanced further than the economic partnership.
AUTHOR’S BIO:
Mathieu Lemoine is a governance, rule of law and public sector reform professional with experience across UNDP, USAID, OSCE, EU institutions and election observation missions. He has worked extensively on governance, elections, civil society and regional dynamics in Central Asia, Eastern Europe and the South Caucasus.
By: Sobir Kurbanov and Eldaniz Gusseinov
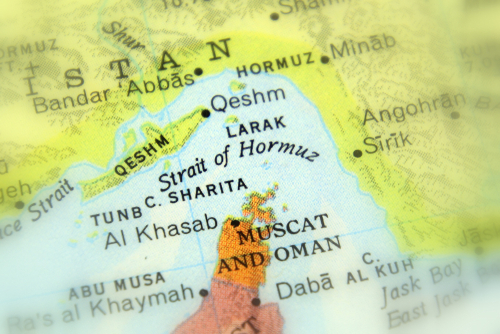
The renewed closure of the Strait of Hormuz, which followed the strikes on Iran of 28 February 2026, has tested world energy markets without producing the price spike that most forecasters expected, and the main reason lies in China. Chinese crude imports fell to 7.1 million barrels per day in June against a 2025 average of 11.6 million, while refinery utilisation dropped to 57.7 percent. For Central Asia the consequence arrives indirectly, because the same weak Chinese demand that has capped crude prices is also depressing the steel, iron ore and ferroalloy prices on which Kazakhstan’s metallurgical sector depends. The chokepoint that Beijing is building Central Asian corridors to bypass is now transmitting its own shock into the region through the very relationship those corridors are meant to deepen.
BACKGROUND:
The Strait of Hormuz carries roughly 20 percent of global oil consumption and a comparable share of liquefied natural gas, with no overland substitute at scale for most Gulf producers. The International Energy Agency warned on 12 August 2026 that Hormuz-related losses would cut global oil supply by 4.3 million barrels per day across the year, and that a projected demand increase of 850,000 barrels per day had reversed into a decline of 1.6 million. Prices rose sharply, yet the escalation that many analysts anticipated did not materialise, because the largest buyer withdrew from the market at the same moment.
On 5 March 2026 China ordered its largest refiners to suspend diesel and gasoline exports, and refiners began cutting throughput and bringing scheduled maintenance forward within days. A structural change compounded the cyclical one. GL Consulting estimates that Chinese gasoline consumption will fall 5.5 percent in 2026, the second steepest decline after the lockdown year of 2022, with retail prices up roughly 30 percent since late February and electric vehicles absorbing a growing share of the fleet. China entered the disruption holding approximately 300 million barrels of cheap crude accumulated over the 14 months before the war, a buffer that is substantial and finite.
Central Asia is too integrated into external markets to insulate itself from a shock of this size, and yet the shock does not arrive directly. Kazakhstan ships most of its crude westward through the Caspian Pipeline Consortium rather than through the Gulf, and the region’s hydrocarbon trade with China moves by pipeline, which protects volumes while leaving prices exposed. External disturbances therefore reach Central Asian economies through three intermediaries, Russia, China and the European Union. Residents of the region learned the shape of that transmission in 2022, when the war in Ukraine reached household budgets through remittances, Russian banking channels and rerouted transit rather than through any direct commercial link. The present episode follows a different path. In Temirtau and Aktobe, where employment is concentrated in steel and ferroalloy plants, and in Karaganda region, the connection between a maritime chokepoint 3,000 kilometres away and local order books is neither obvious nor remote.
IMPLICATIONS:
The transmission runs through Chinese construction. China accounts for roughly half of world steel output, and construction absorbs about 49 percent of that steel, down from 58 percent in 2020. The property downturn has deepened rather than stabilised. Between January and May 2026, housing sales declined 10.8 percent by floor area and 13.5 percent by value, new construction starts fell 22.6 percent and property investment fell 16.2 percent. Weak demand for steel pulls down the inputs that Kazakhstan sells into it.
According to analysis published by the Kazakh sector channel Metals and ESG Trends.KZ, falling steel demand has depressed prices for iron ore, ferrochrome, silicomanganese and ferrosilicon, with ferrosilicon down by approximately 30 to 35 percent and pressure building on Qarmet, ERG and the country’s independent ferroalloy producers. These figures come from a sector channel rather than from exchange data and should be treated as indicative, though they are consistent with the direction of Chinese construction indicators.
The oil shock is mainly a reversible supply-and-refinery disruption, although China’s underlying oil-demand trend is weakening. The ferrous challenge is more structural: China’s property sector is unlikely to restore the previous steel-demand regime, while Chinese overcapacity may intensify competition in Kazakhstan’s surrounding markets. Kazakhstan therefore needs not only short-term support, but a multi-year strategy of market diversification, productivity improvement and product upgrading.
The more consequential implication concerns the logic of integration itself. Chinese investment in processing industries across Central Asia has reached an estimated US$ 11.8 billion against US$ 4.1 billion in energy, reversing the historically extractive pattern, and the China-Kyrgyzstan-Uzbekistan railway began construction in 2025. Nightingale Int. argued in October 2024 that Beijing would move from buying commodities in the region to embedding it in Chinese industrial chains, a forecast that BYD’s full localisation of electric vehicle production in Uzbekistan has since borne out. That investment is driven substantially by the same chokepoint exposure now visible at Hormuz. Central Asia is therefore receiving Chinese capital because China needs a continental rear, and absorbing Chinese demand shocks because it is becoming one. Deeper integration raises both the opportunity and the correlation.
Transit revenue moves with the same cycle, since corridor volumes through Central Asia are weighted toward Chinese cargo, and traffic on the Trans-Caspian Transport Corridor reached 4.5 million tonnes in 2024 before easing in 2025. Kyrgyzstan and Tajikistan face a different version of the problem. Neither exports ferroalloys at scale, and both carry sovereign debt to China equivalent to roughly 9.5 percent and 6 percent of GDP respectively, servicing obligations denominated against a creditor whose own fiscal position is tightening. A prolonged Chinese slowdown compresses their repayment capacity and their construction pipelines at once.
Kazakhstan’s emerging answer is visible in Karaganda region, where new copper extraction and processing projects are advancing and diversification into non-ferrous metals has become a working scenario for the sector. The direction is sound, and the caveat is familiar. Announced projects are not deployed capacity, and copper demand is itself concentrated in Chinese buyers. Diversification that changes the commodity while leaving the customer unchanged reduces exposure to one construction cycle and not to one counterparty.
CONCLUSIONS:
The Hormuz disruption has demonstrated that Central Asia’s exposure to global shocks is now mediated primarily through China, and that this channel operates in both directions. Beijing’s search for continental redundancy is drawing capital, factories and corridors into the region, while the maritime vulnerability that motivates that search transmits demand shocks back along the same route. If flows through the strait normalise within 2026, the oil-linked component will unwind. The ferrous component will not, because it rests on a Chinese property contraction that predates the conflict and is expected to persist. For Central Asian governments the practical lesson concerns buyers rather than corridors. Multi-vector policy has been articulated mostly in terms of routes and creditors, and the present episode indicates that the diversification that matters most is the diversification of demand.
AUTHOR’S BIOS:
Sobir Kurbanov is an international development expert and fellow at Nightingale Int. with over 20 years of experience in partnership-building, complex market reforms, program management, and teaching policy reform, public sector economics, and industrial policy across Eurasia. His expertise spans macroeconomic management, public sector governance, private sector development, trade, investment climate, infrastructure, and IF4D portfolio management, with a strong track record of working with bilateral and multilateral donors (SECO, DFID, USAID, IMF, WB, EU, UN), governments, CSOs, and think tanks, and leading cross-functional teams to advance evidence-based policy solutions.
Eldaniz Gusseinov is co-founder and Head of Research at Nightingale Int. and a non-resident fellow at Ibn Haldun University’s Haydar Aliyev Center for Eurasian Studies.
Feature Articles
|
Earlier Articles
|
The Central Asia-Caucasus Analyst is a biweekly publication of the Central Asia-Caucasus Institute & Silk Road Studies Program, a Joint Transatlantic Research and Policy Center affiliated with the American Foreign Policy Council, Washington DC., and the Institute for Security and Development Policy, Stockholm. For 15 years, the Analyst has brought cutting edge analysis of the region geared toward a practitioner audience.
Sign up for upcoming events, latest news, and articles from the CACI Analyst.